Total-ly Out of Control
by Douglas Begin, MABA Vice President
A vehicle owner can do everything right: maintain the car, pay the insurance premium and finally make that last loan payment.
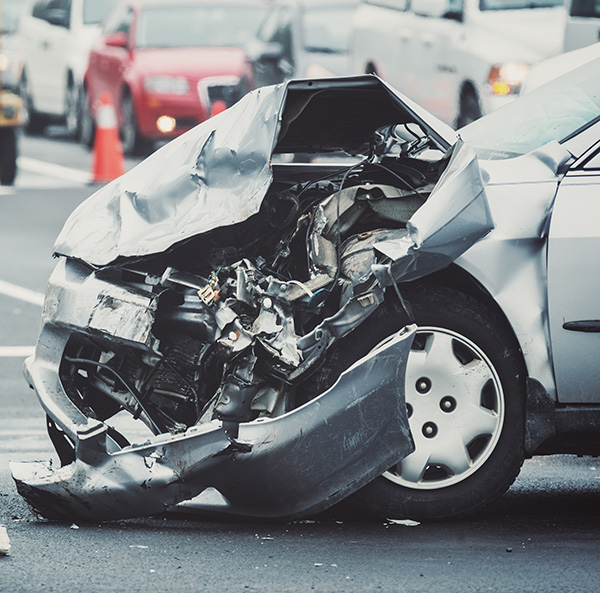 Then one accident changes everything. The vehicle is declared a total loss, and suddenly that owner is shopping for a replacement and facing a monthly payment they thought was behind them.
For Massachusetts collision repairers, total losses are a growing concern that deserves more than a conversation about storage charges. We need to examine how these decisions are made, whom they benefit and what they cost the people we serve.
The national trend is significant. CCC Intelligent Solutions’ 2026 Crash Course report puts total loss frequency at a record 23.1 percent of claims across all loss categories. That is national data, not a Massachusetts statistic, and aging vehicles, repair costs and changing claim behavior all contribute. But it reinforces the urgency of reviewing our own rules.
Under Massachusetts regulation 212 CMR 2.04(1)(f), an insurer may deem a vehicle a total loss when the appraised repair cost plus estimated salvage value can reasonably be expected to exceed its actual cash value. The regulation also expressly prohibits determining a total loss through a percentage formula. I believe that prohibition deserves reconsideration.
Consider a hypothetical vehicle worth $20,000 before an accident, with $11,500 in repairs and an estimated salvage value of $9,000. The combined figure is $20,500. The formula permits a total loss even though repairs represent just 57.5 percent of the vehicle’s value. A higher salvage estimate can shrink the amount available for repair.
That arithmetic may make sense on an insurer’s balance sheet. It deserves closer scrutiny when it determines whether a consumer loses a vehicle that could otherwise be safely repaired. Salvage recovery should not carry more weight than a sound repair plan and the owner’s financial well-being.
Rhode Island offers a useful model. Its law compares repair costs with pre-loss fair market value and gives consumers a total-loss option when repairs reach 75 percent but remain below 80 percent. It also permits a lower-percentage total loss at the owner’s request with express written authorization. Exceeding 80 percent does not automatically require a total loss.
Massachusetts should consider adopting a similar percentage-based approach: an 80 percent baseline restricting insurer-initiated economic total losses, an owner’s option between 75 and 80 percent, and informed written consent for voluntary totals below that range. For safely repairable vehicles, the calculation should compare the complete repair cost directly with a properly established pre-loss value, without adding salvage recovery to push the vehicle over the line.
That would give consumers and repairers a clearer standard. In our $20,000 example, the $11,500 repair would fall well below an 80 percent threshold of $16,000. A strong salvage bid alone would no longer determine whether the owner loses that vehicle.
An actual cash value settlement is not a promise of a brand-new vehicle. Even a fair settlement can leave an owner confronting limited replacement choices, financing costs and another loan. If a loan balance consumes much of the settlement, the money available to replace transportation can be even tighter.
For a family already balancing housing, groceries, utilities and childcare, that additional payment can be devastating. Consumer advocates should stand beside collision repairers in this discussion. Preserving access to a safely repaired vehicle can protect a household from an unplanned financial commitment.
We also need to look honestly at our own businesses. Legitimate total loss charges compensate shops for work performed, space occupied and resources committed. There can be a decent net profit in those charges. Repairers should document and collect what they have earned.
However, those dollars cannot become the foundation of a healthy revenue stream. Total loss activity does not consistently sustain technician production, paint department utilization, parts sales or the skills developed through completing repairs. A profitable individual file can still represent lost opportunity across the business. Building a shop around vehicles leaving on a salvage truck is a fragile strategy.
Percentage reform must preserve complete repairs to manufacturer requirements. Estimates must include necessary procedures, and vehicle valuations must be fair and transparent. No threshold should force an unsafe repair or require shortcuts to keep a vehicle below the limit. Owners should receive the valuation and repair calculation in writing, with a meaningful opportunity to challenge errors before a total loss decision commits them to replacing their means of transportation.
Collision repairers and consumer advocates should bring this proposal to Massachusetts lawmakers and regulators together. A Rhode Island-style framework offers a practical starting point for protecting owners, supporting safe repairs and reducing salvage-driven total losses.
When a repairable vehicle becomes an unaffordable replacement obligation, the current approach has become total-ly out of control.
Want more? Check out the November 2026 issue of New England Automotive Report!